Inherited Annuity Options and Taxes (2026)
Inherited annuity options and taxes: lump sum, five-year rule, stretch payments, and spousal continuation, plus what to ask the insurer.
October 5, 2026
If you inherited an annuity, your choices usually depend on the contract, your relationship to the person who died, and whether the annuity was qualified or nonqualified. Common inherited annuity options include a lump sum, payouts over five years, life expectancy payments, and spousal continuation for a surviving spouse.
The tax result can change a lot depending on the payout you choose. Before signing the insurer's claim form, ask for every available option in writing and consider speaking with a tax professional. This article is general information for beneficiaries, not legal or tax advice.
First, confirm what you inherited
An annuity is a contract with an insurance company. The person who bought it may have been the owner, the person receiving payments may have been the annuitant, and the person listed to receive money after death is the beneficiary. Sometimes one person fills all roles. Sometimes the roles are split, which can affect what happens next.
Start by confirming:
- The insurance company name
- The contract number
- Whether you are listed as a primary or contingent beneficiary
- Whether there are other beneficiaries
- Whether the annuity is inside an IRA, 401(k), 403(b), or other retirement plan
- Whether payments had already started before the death
- Whether the estate, a trust, or a person is named as beneficiary
If you are a named beneficiary, the annuity often passes by beneficiary designation instead of through probate. If the estate is the beneficiary, the executor may need to claim it for the estate and distribute it under the will or state law. If a trust is the beneficiary, the trustee may need to act.
During the estate settlement, annuities can be missed because families may not see a bank account with a clear balance. The clue may be an old policy, a tax form, or a monthly deposit in the deceased person's checking account.
Common annuity beneficiary payout options
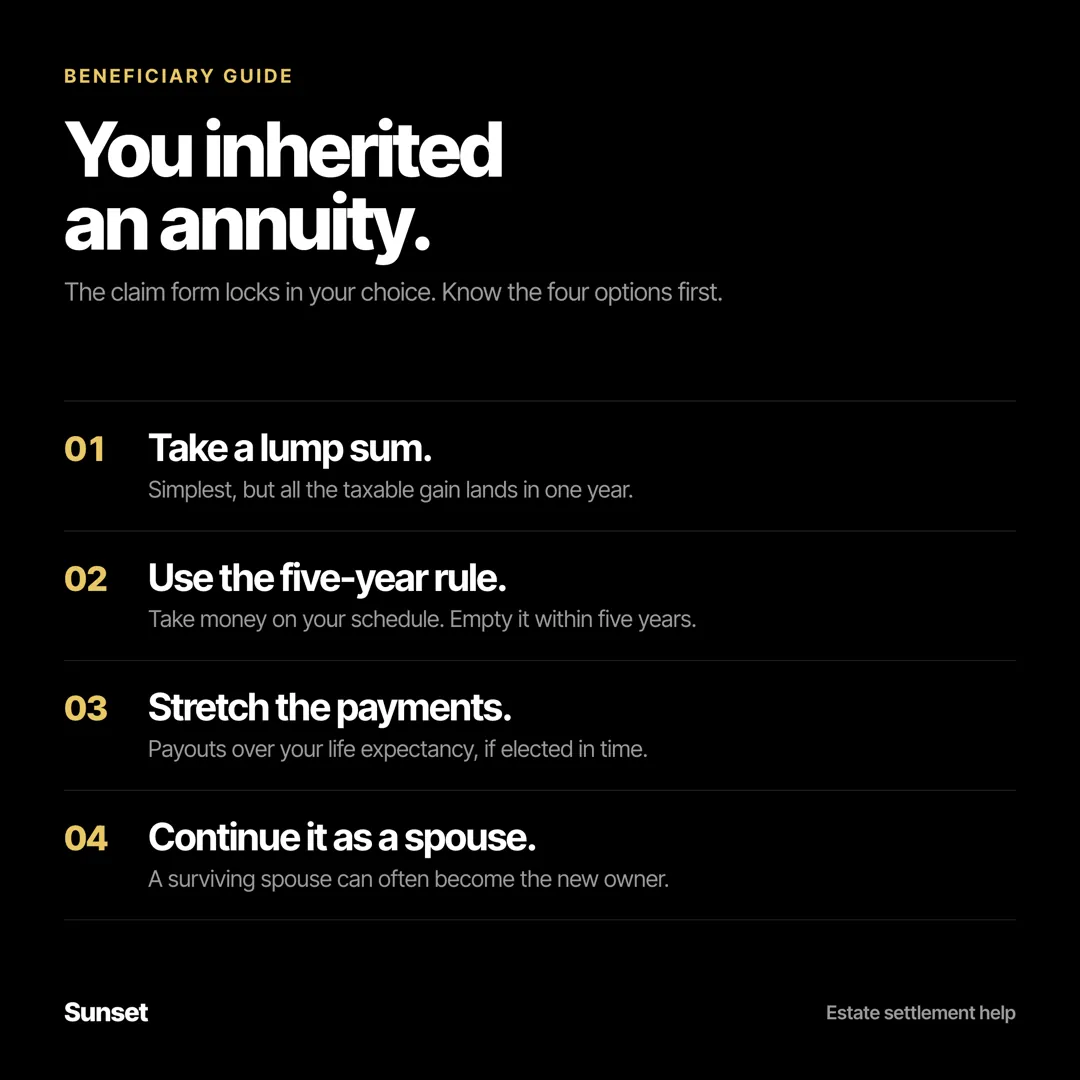
The insurer will usually send a claim packet after receiving the death certificate. That packet may list several annuity beneficiary payout options. The choices below are common, but the contract controls what is offered.
| Option | How it usually works | What to think about |
|---|---|---|
| Lump sum | You receive the full death benefit at once | Simple, but taxable income may be concentrated in one year |
| Five-year payout | You take money in installments or at any time, as long as the account is emptied by the required deadline | Can spread income, but the full balance must be paid out on time |
| Stretch or life expectancy payments | You receive payments over your life expectancy if the contract and tax rules allow it | May reduce yearly taxable income, but deadlines can be strict |
| Spousal continuation | A surviving spouse may be able to continue the annuity as the new owner | Can preserve tax deferral and existing benefits, if allowed |
A lump sum may feel easiest when bills are waiting. It can also push more taxable income into one year, which may affect your tax bracket, Medicare premiums, or state taxes.
The five-year rule is often seen with nonqualified annuities. In many cases, the inherited contract must be fully distributed within five years of death unless a life expectancy payout begins within the required time and the contract allows it. Qualified annuities held inside retirement accounts can follow different rules, including the inherited retirement account rules discussed in Sunset's guide to inherited IRA and 401(k) options.
Stretch payments can help spread taxable income, but they are not always available. The insurer may require the election within a short window. If you miss the deadline, the choice may disappear.
Spousal continuation is different. A surviving spouse may be able to step into the contract and keep it going. This can be valuable if the contract has an income rider, a death benefit rider, or older guarantees. The spouse should ask what benefits continue, what fees apply, and what happens if the contract is later surrendered.
Inherited annuity taxes: qualified vs nonqualified
Inherited annuity taxes depend first on whether the annuity was qualified or nonqualified.
A qualified annuity is held inside a tax-favored retirement account, such as an IRA, 403(b), or qualified employer plan. In many cases, distributions from a qualified annuity are taxed as ordinary income because the original owner used pre-tax money. There may be exceptions if after-tax contributions were made, but many beneficiaries should expect the full taxable portion to appear on Form 1099-R.
A nonqualified annuity was bought with after-tax money outside a retirement account. With a nonqualified annuity, the original investment in the contract is generally not taxed again. The gain is taxed as ordinary income when paid out. For example, if the person paid $80,000 into a nonqualified annuity and the death benefit is $120,000, the $40,000 gain may be taxable as ordinary income to the beneficiary. The numbers can be more complex if payments had already started.
Unlike many inherited stocks or homes, annuities generally do not receive a full step-up in basis at death. This is a common surprise. The taxable gain inside a nonqualified annuity can remain taxable to the beneficiary.
The insurer reports distributions on Form 1099-R. You may be able to choose federal and state withholding on the claim form. Withholding is not the same as the final tax bill. If the payout is large, ask a tax professional whether estimated tax payments are needed. Sunset's overview of tax filings after a death explains how final individual returns, estate income tax returns, and state requirements can fit together.
Why the insurer's claim form matters so much
The claim form is more than paperwork. It is often the document that locks in your payout choice.
Before signing, ask the insurer for:
- A written list of every payout option available to you
- The deadline for each election
- The taxable amount expected under each option, if the insurer can provide it
- Whether choosing a lump sum ends any riders or guarantees
- Whether spousal continuation is available
- Whether the annuity is qualified or nonqualified
- Whether your election can be changed after processing
- How federal and state withholding will be handled
Be careful with default choices. Some forms put the lump sum on the first page because it is easy to process. That does not mean it is the best option for you.
If there are multiple beneficiaries, each beneficiary may have separate choices, or the contract may require all beneficiaries to use the same payout method. Ask before assuming. If a minor child, estate, or trust is involved, the process may take longer and may require court papers or trustee documents.
If you are also the executor, separate your roles. As beneficiary, you may be claiming an asset that passes directly to you. As executor, you may be responsible for estate bills, probate filings, and tax paperwork. Sunset's what to do when someone dies checklist can help you sort immediate tasks from later estate work.
How to find annuity contracts after a death
Families often know about checking accounts and life insurance, but annuities can be harder to spot. A contract may have been bought years ago, and the insurer name may have changed after a merger.
Look for clues in:
- Prior tax returns with Form 1099-R
- IRS wage and income transcripts
- Bank deposits labeled with an insurer name
- Bank withdrawals or premium payments
- Mail from insurance companies
- Old financial advisor statements
- A safe deposit box or home files
- Email records and online password managers
A 1099-R history is especially useful. If the deceased person received annuity payments, the insurer likely issued a 1099-R each year. Even if the contract has since changed, the payer name can give you a starting point.
Sunset searches 2,500+ financial institutions to help families find accounts and assets, including clues that may point to annuity contracts. Sunset can also help organize what has been found, generate state- and county-specific probate packets when probate is needed, and refer families to a local probate attorney when counsel is needed. For estate funds, Sunset offers an FDIC-insured estate account. When assets are ready to be distributed, Sunset helps families track transfers to beneficiaries and heirs.
Sunset has helped 15,000+ families settle estates, including families who found financial accounts only after reviewing tax forms and transaction history.
What to do before choosing a payout
You do not need to solve everything the day the claim packet arrives. A short pause can prevent a costly mistake.
Before you choose:
- Get the contract type in writing. Ask whether the annuity is qualified or nonqualified.
- Ask for all options, not just the form in front of you.
- Confirm deadlines for the five-year rule, life expectancy payments, or retirement account rules.
- Estimate taxable income under each option.
- Ask whether any riders, guarantees, or bonuses are lost if you take cash.
- Review whether other estate issues affect timing, such as probate, creditor claims, or a trust.
- Save every letter, claim form, and 1099-R.
If the insurer says only one option is available, ask why. It may be true, but you want the reason tied to the contract or tax rule, not a processing shortcut.
FAQ
Do beneficiaries pay taxes on an inherited annuity?
Often, yes. A qualified annuity is usually taxable as ordinary income when paid out. A nonqualified annuity is usually taxable only to the extent the payout is more than the original investment in the contract. The insurer reports distributions on Form 1099-R.
Can I stretch an inherited annuity?
Maybe. Some nonqualified annuities allow life expectancy payments if the election is made on time. Qualified annuities inside IRAs or workplace plans may be subject to inherited retirement account rules, which can limit stretch treatment for many non-spouse beneficiaries.
Does an inherited annuity go through probate?
If a living beneficiary is named, the annuity often passes directly to that beneficiary outside probate. If the estate is named, no beneficiary survives, or the contract requires estate payment, the executor may need to claim it through the estate.
Is a lump sum the best inherited annuity option?
It depends on your cash needs, tax situation, and the contract. A lump sum is simple, but it may create a larger tax bill in one year. Ask for the tax reporting estimate and compare it with the five-year or life expectancy options.
What if I cannot find the annuity contract?
Start with old tax returns, 1099-R forms, bank records, financial advisor statements, and mail from insurers. Sunset can help search across financial institutions and use 1099-R history and transaction clues to find accounts that may otherwise be missed.
Sunset can help you find and organize estate assets
An inherited annuity can be valuable, but the right next step depends on details hidden in the contract and claim form. Take time to confirm the annuity type, compare payout choices, and understand the tax reporting before you sign.
Sunset can help families find accounts and assets, prepare probate paperwork when needed, open an FDIC-insured estate account, and track transfers to beneficiaries and heirs. If a probate attorney is needed, Sunset can refer you to local counsel.